Central Florida home insurance is a purchase decision, not a closing afterthought, for Horizon West and Clermont buyers. Premiums, deductibles, wind and flood exposure, roof condition, construction details, HOA responsibilities, and lender requirements can materially change the real cost of a home. Get a property-specific quote before your inspection period ends, and verify flood maps, insurance history, roof documentation, and association responsibilities through the insurer, county records, HOA documents, and FEMA resources.
Have a question about Central Florida home insurance reality check for Horizon West and Clermont buyers? Reach out to Sol Simpson at Florida Homes Group: local knowledge, straight answers, no pressure.
In This Guide
Central Florida home insurance reality check for Horizon West and Clermont buyers starts with one clear position: do not evaluate a home using the mortgage payment alone. A property that appears affordable at the offer stage may carry a very different monthly obligation after wind coverage, flood coverage, deductibles, escrow requirements, and HOA responsibilities are confirmed.
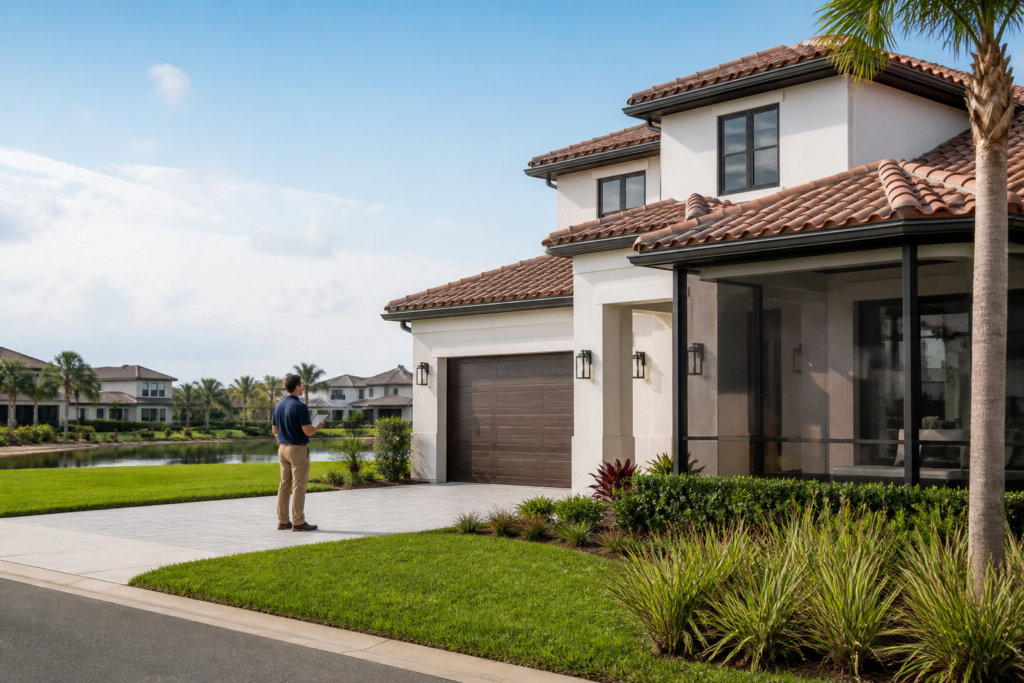
Horizon West and Clermont are close geographically, but insurance outcomes can vary by address, construction type, roof age, elevation, drainage, prior claims, and the insurer’s underwriting rules. The right approach is to obtain a quote tied to the exact property before you become financially committed, then use the inspection and contract timelines to investigate anything that changes coverage or affordability.
Why Insurance Changes the Buying Decision
Insurance is part of the home’s operating cost and should be treated with the same seriousness as taxes, HOA fees, CDD fees, utilities, and maintenance. A lender may require proof of coverage before closing, but the lender’s approval does not mean the policy is broad, inexpensive, or well suited to your risk tolerance.
In Horizon West, buyers may be comparing newer homes in planned villages with resale properties that have different roof ages, building materials, wind mitigation features, and claims histories. In Clermont, topography, lakes, drainage patterns, older construction, and neighborhood-specific flood exposure can create a different underwriting conversation from one property to the next.
For broader market context, Redfin reported a Horizon West median sale price of approximately $588K and an average of about 40 days on market, based on its rolling three-month update through July 2026. Those figures help explain the purchase environment, but they do not predict an individual property’s insurance premium or confirm that a home is financially comfortable for a particular buyer.
- Ask for a quote using the exact address, not a nearby property or an online estimate.
- Confirm the dwelling limit reflects replacement cost rather than only the contract price.
- Review wind, hurricane, water, contents, liability, and loss-of-use coverage separately.
- Understand the difference between a standard deductible and a named-storm or hurricane deductible.
- Ask whether the insurer requires roof, electrical, plumbing, or inspection documentation before binding coverage.
Central Florida home insurance reality check for Horizon West and Clermont buyers also means separating the home’s market value from its insurable value. Land, location, finishes, and buyer demand influence price, while rebuilding materials, labor, code requirements, debris removal, and specialized features influence the amount of coverage required.
How to Check the Real Cost
The most useful insurance review happens early, while you still have time to investigate the property and make a contractual decision. Ask your insurance professional to quote the address using the seller’s available information, then update the quote after inspection findings, roof documentation, permits, and mitigation features are confirmed.
For Central Florida home insurance reality check for Horizon West and Clermont buyers, the critical issue is not simply finding the lowest initial premium. A low quote can be less useful if it carries restrictive coverage, high deductibles, limited water protection, inadequate replacement-cost treatment, or conditions that cannot be satisfied before closing.
- Request the seller’s current declarations page, if available, and ask whether the policy has had coverage restrictions or nonrenewal notices.
- Ask the insurer whether the roof age and remaining useful life meet current underwriting requirements.
- Confirm whether the property is in a special flood hazard area using FEMA’s official flood map tools, while remembering that flooding can occur outside mapped zones.
- Review the county property appraiser and public records for permits, additions, enclosures, roof work, and other improvements that may affect replacement cost.
- Request the HOA or condominium association’s insurance summary and determine which items are covered by the association versus the individual owner.
- Ask the lender to model the full escrow payment after the insurance quote is received, rather than relying on an early estimate.
New construction does not eliminate insurance questions. Buyers should ask the builder or sales representative for roof permits, product specifications, warranty information, wind mitigation documentation, elevation information when relevant, and the process for correcting construction issues that could affect underwriting.
Builder incentives vary by builder and location: confirm current offers and eligibility directly with the builder or their affiliated lender, as these change frequently.
Let’s discuss your move.
Call us at (407) 680-3210 or book a free 15-minute call. We’ll tell you exactly what we’d look for based on your situation.
“I’ve known Steve as a hard working, trustworthy and successful businessman for the past thirty five years. He goes above and beyond for his clients and his staff and nothing is ever too much trouble. Based on his business ethics I would fully recommend Steve.”
Steve Drake · Google Review
Have a question about Central Florida Home Insurance Reality Check?
Ask it here and a Florida Homes Group agent will answer you personally, usually the same day. No pressure, no sales pitch.
What to Inspect Before You Commit
Insurance and inspection should work together. The inspection identifies physical conditions, while the insurance review determines whether those conditions create a coverage limitation, a premium concern, a required repair, or a lender issue.
For Central Florida home insurance reality check for Horizon West and Clermont buyers, pay particular attention to the roof, attic, exterior openings, drainage, water intrusion, electrical panels, plumbing supply lines, air-conditioning equipment, pools, screened enclosures, retaining features, and detached structures. Ask the inspector to document age, condition, visible damage, and any item that may require a specialist.
- Confirm that roof permits and replacement records match the seller’s statements and county records.
- Ask whether impact-rated windows, shutters, roof attachments, garage doors, or other mitigation features are documented well enough for the insurer to recognize them.
- Check for signs of prior water intrusion, recurring moisture, grading concerns, or drainage paths around the structure.
- Identify improvements that may not have been included in the original builder or county records.
- Review pool, dock, seawall, lake access, outdoor kitchen, and detached structure coverage rather than assuming the main dwelling policy handles everything.
- Request written answers when an insurer, builder, HOA, seller, or contractor makes a coverage or repair representation.
In a resale transaction, do not assume the seller’s current premium will transfer to you. The insurer may reassess the property, the buyer’s underwriting profile, the roof documentation, the coverage limits, and the replacement-cost assumptions after the sale.
In a new construction transaction, ask who is responsible for correcting documentation gaps before closing. A buyer should not wait until the lender or insurance carrier raises an issue at the end of the process.
Central Florida home insurance reality check for Horizon West and Clermont buyers is ultimately a documentation exercise. The strongest file includes the quote, declarations page when available, inspection report, mitigation documents, permits, HOA insurance summary, flood information, and written answers to open questions.
What to verify before making the decision:
- Current coverage availability with a licensed insurance professional.
- Property-specific flood information through FEMA and the relevant county resources.
- Roof age, permits, mitigation features, and claims history where available.
- HOA, master association, or condominium insurance responsibilities in the governing documents.
- Current taxes, assessments, HOA fees, and CDD fees through county records and association disclosures.
Field Insights
Buyers often receive a preliminary insurance quote before the inspection, then discover that roof age, missing permits, flood exposure, or association responsibilities change the policy after they have emotionally committed to the home.
Obtain the address-specific quote early, connect it to the inspection findings, and keep a written verification list. In Horizon West and Clermont, the best decision is the one that accounts for the property’s actual documents and physical condition, not a generic neighborhood estimate.
Ready for Clarity on Your Next Move?
Central Florida home insurance reality check for Horizon West and Clermont buyers should happen before price and payment assumptions become fixed. Florida Homes Group can help you organize the property, contract, inspection, HOA, and local market questions so you can make a more informed decision. Bring us the address and the issues you are weighing, and we will help you identify the next verification step.
Have a question about Central Florida Home Insurance Reality Check?
Ask it here and a Florida Homes Group agent will answer you personally, usually the same day. No pressure, no sales pitch.
Frequently Asked Questions
When should buyers request an insurance quote in Horizon West or Clermont?
Request a property-specific quote as soon as you identify a serious candidate, and do not wait until the final days before closing. Update the quote after the inspection and after roof, permit, flood, HOA, and mitigation information is confirmed.
Is flood insurance automatically included in a homeowners policy?
Do not assume it is included. Ask a licensed insurance professional what water-related coverage applies, verify the address through FEMA flood map resources, and review whether the property’s location, drainage, elevation, or nearby water features create additional concerns.
Can a newer home still have insurance problems?
Yes. Newer construction can still require documentation for the roof, wind mitigation features, permits, elevation, construction materials, and association responsibilities. Ask the builder and insurer what records are required before closing, and obtain written confirmation when a detail affects coverage.