What should Horizon West buyers verify before insuring a new construction home in Central Florida?
New construction home insurance in Central Florida should be arranged before closing, but the first quote is not enough. Confirm the replacement cost, wind and flood exposure, roof and opening protections, construction details, mortgage requirements, HOA or CDD responsibilities, and the final policy exclusions with a licensed Florida insurance agent. Verify current premiums, eligibility, inspection requirements, and flood zone information directly with the agent, the builder, FEMA or county records, and your lender.
Have a question about new construction home insurance in Central Florida? Reach out to Sol Simpson at Florida Homes Group: local knowledge, straight answers, no pressure.
In This Guide
Before You Request Quotes for New Construction Home Insurance in Central Florida
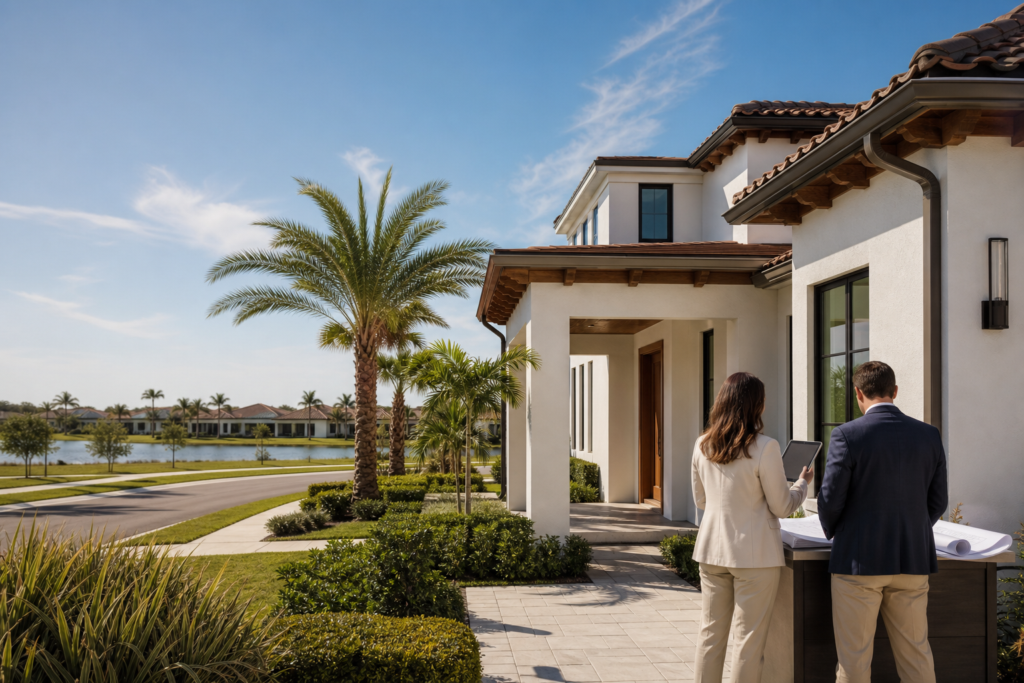
Start the insurance process as soon as the builder provides a reliable construction profile, not the day before closing. A licensed agent will need more than the community name, especially in Horizon West, where homes may sit under different municipal jurisdictions and may have different flood, wind, HOA, and CDD considerations.
Ask the builder or closing team for the information below. Request it in writing so the insurance quote is based on the actual home rather than a rough estimate.
- Street address, legal description, and the applicable city or county jurisdiction.
- Builder name, floor plan, heated living area, total roof area, and construction type.
- Year built, expected completion date, permit status, and certificate of occupancy timing.
- Roof covering material, roof shape, installation documentation, and warranty information.
- Exterior wall construction, window type, garage door specifications, and opening protection details.
- Electrical, plumbing, HVAC, fire protection, and security features.
- Elevation certificate or other flood-related documentation, when available.
- HOA documents, community insurance responsibilities, and any CDD information supplied by the seller or builder.
Do not assume that a new roof means a low premium or that a recently built home is automatically easy to insure. New construction can help with some underwriting questions, but location, replacement cost, wind exposure, flood risk, carrier appetite, deductibles, and policy terms still control the final result.
What Your Policy Must Address
The right policy is not simply the one with the lowest quoted premium. For new construction home insurance in Central Florida, compare the coverage structure, exclusions, deductibles, endorsements, and claims process alongside the price.
Replacement cost and dwelling coverage
Ask how the dwelling limit was calculated and whether it reflects current reconstruction costs rather than the purchase price or appraised value. Land, the lot, and some site characteristics are not insured in the same way as the structure, so a home price should never be used as a substitute for a replacement cost estimate.
Confirm whether extended replacement cost coverage is available and understand its conditions. Ask how detached structures, built-in upgrades, custom finishes, pools, screened enclosures, outdoor kitchens, and permanently installed equipment are treated.
Wind, hurricane, and named storm coverage
Review the windstorm and hurricane deductible carefully. It may be different from the all-other-perils deductible, and the policy may define covered wind events in a way that affects your out-of-pocket exposure.
Ask the agent to identify the documents needed for wind mitigation credits. Builder specifications, permit records, product approvals, inspection reports, and opening protection documentation may all matter. Never assume a feature qualifies until the carrier confirms it.
Flood and water exposure
Standard homeowners insurance generally does not replace a dedicated flood policy. Ask whether the address is in a mapped flood area, but do not stop there because drainage, stormwater design, finished-floor elevation, nearby lakes, retention areas, and lender requirements can also affect the decision.
For a home near a lake, pond, canal, or drainage feature in Horizon West, ask the insurance agent and the appropriate county or municipal office which records should be reviewed. Confirm who maintains nearby stormwater infrastructure and whether the HOA has documents that explain shared responsibilities.
Water damage and liability details
Ask about water backup, sudden plumbing failures, mold limitations, matching of undamaged materials, personal property coverage, loss of use, and personal liability. These details can be more useful than a broad promise that the home is covered.
Also verify whether the builder warranty, appliance warranties, and homeowners policy respond to different problems. Insurance is not a substitute for correcting construction defects, and the builder warranty does not replace property insurance.
Let’s discuss your move.
Call us at (407) 680-3210 or book a free 15-minute call. We’ll tell you exactly what we’d look for based on your situation.
“I’ve known Steve as a hard working, trustworthy and successful businessman for the past thirty five years. He goes above and beyond for his clients and his staff and nothing is ever too much trouble. Based on his business ethics I would fully recommend Steve.”
Steve Drake · Google Review
Have a question about New Construction Home Insurance in Central Florida: A?
Ask it here and a Florida Homes Group agent will answer you personally, usually the same day. No pressure, no sales pitch.
Builder, Closing, and Local Verification
Insurance is part of the new construction purchase process, not an administrative task after the contract is signed. The builder, lender, title company, HOA, county, and insurance agent may each hold a different piece of the information you need.
Ask the builder targeted questions
- Which roof, window, garage door, and exterior construction standards apply to this homesite?
- Can the builder provide permit records, product approvals, inspection documents, and wind mitigation information?
- Are there developer-installed features that affect flood drainage, retaining walls, ponds, or common-area structures?
- Which items are covered by the builder warranty, and which are expressly excluded?
- Will any closing delay change the insurance binder, occupancy date, or lender approval?
Coordinate with the lender
Your lender will usually require proof of insurance before closing and may have specific requirements for deductibles, replacement cost, mortgagee wording, and flood coverage. Send the quote and binder to the lender early enough to resolve discrepancies without putting the closing date at risk.
Ask whether the lender has accepted the carrier and policy structure. A quote that looks complete to a buyer may still need revised documentation before the lender can approve it.
Review the local documents
Horizon West spans portions of Winter Garden, Windermere-adjacent areas, and Orlando municipal overlap within West Orange County. The mailing address alone may not tell you which public records, permitting office, flood map, or taxing authority applies to the home.
- Use county property records and the applicable municipal office to confirm the parcel and jurisdiction.
- Review FEMA flood map information and ask the insurance agent how the carrier evaluates the address.
- Read the HOA declaration, maintenance responsibilities, insurance provisions, and architectural rules.
- Confirm CDD assessments, community facilities, and any obligations disclosed in the purchase documents.
- Request current insurance terms directly from a licensed agent because carrier availability and underwriting rules change.
For buyers comparing Horizon West new construction with resale homes in Winter Garden real estate or nearby Windermere homes, insurance should be included in the monthly ownership analysis. A newer home may have different maintenance and underwriting considerations, but the location and policy terms still deserve a property-specific review.
Field Insights
Buyers often receive a builder specification sheet, a lender checklist, and an insurance quote that do not use the same descriptions. A missing roof document, unclear opening protection detail, or incorrect jurisdiction can create a late underwriting question just as the closing process is tightening.
Build one property file with the contract, floor plan, site plan, builder specifications, permit records, HOA documents, CDD disclosures, and insurance correspondence. Send the same file to the agent and lender, then ask both to confirm that the address, construction details, deductibles, and mortgagee information match before the final walkthrough.
That documentation habit is especially valuable when buying new construction home insurance in Central Florida from out of state. It gives you a clear record of what was represented, what was verified, and what still needs a written answer before you close.
Ready for Clarity on Your Next Move?
New construction home insurance in Central Florida should be treated as a property-specific due diligence item, not a last-minute quote. Florida Homes Group can help you organize the Horizon West questions around the builder contract, community documents, closing timeline, and long-term ownership plan. When you are ready, we would be glad to help you approach the decision with a clear local framework.
Have a question about New Construction Home Insurance in Central Florida: A?
Ask it here and a Florida Homes Group agent will answer you personally, usually the same day. No pressure, no sales pitch.
Frequently Asked Questions
When should a Horizon West buyer start arranging insurance?
Start when the builder can provide the address and meaningful construction details, then update the quote as completion information becomes available. Do not wait until the final closing appointment, because the lender must review proof of coverage and underwriting questions can take time to resolve.
Is flood insurance required for every new construction home in Horizon West?
No single rule applies to every address. Ask a licensed insurance agent to review the property, check current FEMA and county information, and confirm the lender’s requirements. A home outside a mapped high-risk area may still deserve a flood discussion because drainage, elevation, nearby water, and policy exclusions matter.
What insurance documents should I request from the builder?
Request the roof and opening specifications, permit records, product approvals, construction details, warranty information, and any wind mitigation or elevation documentation available for the property. Have the insurance agent confirm which documents support underwriting or credits instead of assuming every builder document changes the policy.